Planning a budget for an RV means starting with a real number, and the clearest one available comes from Progressive, November 2024. Recreational vehicle (RV) insurance averages $594 per year for a travel trailer and $1,052 per year for a motorhome. Your own premium will move up or down with your RV class, how you use it, and the coverage you choose, and this guide breaks down each of those factors.
This is general information, not financial advice.
Average RV Insurance Cost by Type
The table below gives the clearest starting point for budgeting. It helps to find your RV type, then read the sections after it to understand what shifts your quote up or down.
| RV Type | Est. Annual Cost | Est. Monthly Cost | Source |
| Travel trailer | $594 | ~$50 | Progressive, Nov 2024 |
| Motorhome (all classes) | $1,052 | ~$88 | Progressive, Nov 2024 |
These figures are estimates, so it helps to confirm current rates with an insurer. Class-level premiums vary widely by insurer, and requesting quotes from at least two carriers gives the most accurate number.
Travel Trailers, Fifth Wheels, and Campers
Towable RVs cost less to insure than motorized ones because they do not need their own liability coverage while being towed. Your tow vehicle’s auto insurance policy covers liability on the road. A standalone travel trailer or fifth wheel policy typically handles physical damage, personal contents, and liability when the unit is unhitched.
Camper insurance, covering pop-up campers and truck campers, generally falls at the lower end of the travel trailer range. These units carry lower purchase values than conventional trailers or fifth wheels, so premiums reflect that.
Class A, B, and C Motorhomes
Motorhomes require their own RV insurance coverage because you drive them independently. Each class carries a different cost profile:
- Class A: The most expensive class to insure. These units carry the highest purchase prices, the largest size profiles, and the greatest repair complexity.
- Class B: Campervans sit at the lower end because of their smaller footprint and lower replacement cost.
- Class C: These fall between the two. Class C motorhomes share a truck chassis with many standard vehicles, which helps keep insurer rates closer to the motorhome average.
What Factors Affect RV Insurance Rates
The Progressive averages above are a starting point, not a quote. Your actual premium can land well above or below them, depending on several factors.
RV Type, Class, and Age
A newer, higher-value motorhome costs more to insure than an older travel trailer or camper. Repair costs rise with size and complexity, so a Class A diesel pusher draws a higher rate than a small fifth wheel. As your RV ages and loses value, your premium often drops with it.
Full-Time vs. Recreational Use
How you use your RV is one of the larger cost drivers. Full-timers, meaning owners who live in their RV for more than six months per year, typically pay more than recreational users. Full-timer insurance policies function more like homeowners coverage: they add personal liability protection and loss-of-use benefits that recreational users generally do not need.
If you are considering full-time RV living and want to understand the broader financial picture, the article on RV vs. house costs covers the full cost comparison in detail.
Where You Park and How You Store It
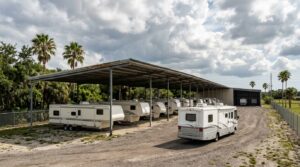
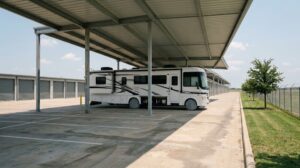
Your storage location is a factor insurers use when calculating comprehensive premiums. An RV kept at a secured, fenced storage facility presents lower theft and weather-damage exposure than one parked on a street or open driveway.
That difference can influence what you pay for comprehensive coverage, though individual insurer policies vary. It helps to ask your insurer directly whether your storage arrangement is reflected in your rate.
Coverage Level and Deductible
A higher deductible lowers your premium. Adding comprehensive and collision coverage raises it.
Some carriers offer liability-only RV coverage for roughly $125 per year, per Progressive’s published figures. That option disappears if your RV is financed. Lenders require continuous comprehensive and collision coverage, whatever the state minimums say.
Driving Record and Claims History
A clean driving record and no recent claims keep your rate at its baseline. Prior at-fault accidents, speeding violations, or a previous RV claim can raise it. Some insurers offer a discount for completing an approved RV safety course, and it helps to ask your carrier whether one is available.
Storage and Lay-Up Coverage: What Seasonal RV Owners Should Know
If your RV sits parked for several months each year, you may not need to pay for full coverage the entire time. A lay-up or storage endorsement lets you suspend collision and liability coverage during months when you are not using your RV. Comprehensive coverage, which protects against fire, theft, and weather damage, stays active.
Storing your RV at a dedicated facility like RecNation’s RV storage can work in your favor. These facilities offer fencing, controlled access, and covered options. Your insurer may treat that storage risk more favorably than a street or driveway location.
Secured storage matters most during lay-up, because comprehensive coverage is the only protection still active.
What a Lay-Up Endorsement Covers
During a lay-up period, collision and liability are suspended. Comprehensive coverage remains in force. You cannot drive the RV during this period: doing so leaves you uninsured for liability and collision.
Some insurers call this a “storage endorsement” or “lay-up discount” rather than a formal endorsement, so it helps to ask your carrier which term they use.
How to Request Lay-Up Coverage
Requesting lay-up coverage follows a simple order of steps:
- Call your insurer before your storage period begins.
- Confirm the start and end dates.
- Get the endorsement confirmed in writing.
- Reinstate full coverage before you move the RV, not after.
- If your RV is financed, check your loan agreement first, since some lenders require continuous full coverage regardless of usage.
Agreed Value vs. Actual Cash Value
If you are still in the process of buying, the article on buying an RV covers depreciation and purchase decisions in detail. The policy structure you choose at purchase affects what you recover if the RV is totaled later.
The two main structures are agreed value and actual cash value (ACV). The table below shows how they differ.
| Factor | Agreed Value | Actual Cash Value |
| Payout at total loss | Pre-agreed amount, no depreciation | Market value at time of loss |
| Depreciation applied | No | Yes |
| Best suited for | Newer, higher-value RVs | Older units with low market value |
| Premium impact | Higher upfront | Lower upfront |
RVs depreciate quickly in the first few years. For a new unit, agreed value protection means a total-loss payout that reflects what you paid, not what the market will give you after that depreciation hits.
Which Policy Type Makes More Sense for Your RV?
Agreed value suits newer and higher-value RVs where depreciation loss would be painful. ACV is acceptable for older units where market value has largely stabilized and the premium savings make sense.
Some lenders require agreed value or replacement cost coverage, so it helps to check your financing terms before choosing.
How to Reduce Your RV Insurance Premium
Several practical steps can lower what you pay before or at renewal. Each one targets a different part of the premium, from the deductible to how many months you are covered.
- Raise your deductible: A higher deductible reduces your monthly payment directly.
- Bundle with auto or home insurance: Many insurers offer multi-policy discounts.
- Maintain a clean driving record: Violations and claims raise your rate at renewal.
- Complete an RV safety course: Some carriers offer a discount, so confirm with your insurer before enrolling.
- Store in a secured facility during the off-season: Secured storage can reduce comprehensive exposure.
- Request a lay-up endorsement: Seasonal owners who park for three to five months can suspend collision and liability, paying for partial-year coverage only.
- Compare quotes from multiple insurers: Rates for the same RV can vary significantly across carriers.
The Storage Endorsement Most RV Owners Miss
The lay-up endorsement is the single most actionable cost-reduction step for seasonal owners. If you park your RV for three to five months and request the endorsement, you pay for liability and collision coverage only during the months you actually drive.
Combined with secured storage, this approach reduces both your premium exposure and the comprehensive risk that stays active year-round.
RV Insurance Requirements by State
Motorized RVs (Class A, B, and C) must carry at least the state minimum auto liability coverage. Towable RVs such as travel trailers, fifth wheels, and campers are generally not required by state law to carry their own liability policy, though lender requirements may still apply.
State minimums change, so it helps to confirm them with the official insurance or motor vehicle site for the state where you register the RV.
| State | Official Source |
| Arizona | Arizona Department of Insurance |
| California | California DMV insurance requirements |
| Florida | Florida Department of Highway Safety and Motor Vehicles |
| Kansas | Kansas Insurance Department |
| Missouri | Missouri Department of Insurance |
| South Carolina | South Carolina Department of Insurance |
| Tennessee | Tennessee Department of Commerce and Insurance |
| Texas | Texas Department of Insurance |
If your RV is financed, your lender’s requirements override state minimums. Expect the lender to require continuous comprehensive and collision coverage regardless of what state law mandates.
Do You Need RV Insurance If You Only Use It Seasonally?
Yes, you still need coverage when you only use your RV seasonally. Comprehensive coverage protects against fire, theft, and weather damage even while the RV sits in storage. A lay-up endorsement lets you suspend liability and collision while it is parked.
If your RV is financed, it helps to review your loan agreement before suspending any coverage. Some lenders require full coverage to stay active year-round.
Final Thoughts on RV Insurance Costs
RV insurance costs come down to your RV type, how you use it, and how much of the year it is actually on the road. Lay-up coverage and secured storage are the two levers seasonal owners most often overlook.
If your RV sits parked for several months between trips, where you store it affects both its condition and how your insurer assesses risk during that period. RecNation operates 70 facilities across Arizona, California, Florida, Kansas, Missouri, South Carolina, Tennessee, and Texas, with outdoor, covered, and enclosed RV storage options sized for travel trailers, fifth wheels, and Class A motorhomes. Prices vary by location, size, and availability.
Frequently Asked Questions
How much does RV insurance cost per month?
RV insurance costs roughly $50 a month for a travel trailer and about $88 a month for a motorhome, based on Progressive’s November 2024 annual averages of $594 and $1,052. Class, coverage level, driving record, and how often the RV is used move the actual monthly figure up or down.
How much is camper insurance?
Camper insurance typically costs less than a conventional travel trailer policy. Pop-up and truck campers are worth less to replace, so their premiums run lower. Progressive’s 2024 travel trailer average of $594 per year is a useful starting benchmark, and older campers often fall below it.
How much does Class A motorhome insurance cost?
Class A motorhome insurance costs more than the $1,052 motorhome average Progressive reported for 2024, because these units have the highest purchase prices and the most liability exposure. Quotes from at least two carriers show the figure for a specific unit.
How much does Class C motorhome insurance cost?
Class C motorhome insurance usually costs less than Class A coverage but more than most travel trailer or camper policies. Class C units are driven independently, so they need their own liability coverage, while the truck chassis keeps rates closer to those of standard vehicles.
Can I suspend RV insurance while my RV is in storage?
A lay-up or storage endorsement lets an RV owner suspend collision and liability coverage while the RV is parked, and comprehensive coverage stays active for fire, theft, and weather damage. Financed RVs may need continuous full coverage, so the loan agreement is worth reviewing first.
Does where I store my RV affect my insurance rate?
Storage location affects RV insurance because insurers weigh theft and weather exposure when pricing comprehensive coverage. A secured storage facility, with fencing, controlled access, and covered or enclosed spaces, typically presents lower exposure than a street or open driveway. Asking your insurer whether your storage arrangement qualifies for any premium consideration confirms what applies to your policy.